Replacing a roof is one of the larger financial decisions a homeowner faces, and the stress of that decision often has less to do with the work itself and more to do with the question of how to pay for it. For homeowners across Winston-Salem, Greensboro, High Point, Kernersville, Clemmons, Rural Hall, King, and Mount Airy, the good news is that financing options have expanded considerably. The harder truth is that not all of those options work the same way, and the differences between them matter far more than most contractor websites let on.
This guide is written to close that gap. By the time you finish reading, you will understand the real distinctions between the financing structures available to you, how your credit profile shapes your options, when each tool is the right one to reach for, and how to sequence the application process so that it works in your favor rather than against it.
A roof replacement is rarely discretionary. When shingles fail, when flashing pulls away, or when a storm accelerates wear that was already developing, the timeline for action is set by the condition of your home, not by your savings account. Financing allows homeowners to protect their property on the correct schedule rather than delaying repairs while emergency funds accumulate.
That said, financing a home repair project is a binding financial commitment, and the terms embedded in contractor financing agreements, bank products, and promotional offers carry real consequences. Understanding the landscape before you sit across from a contractor or a lender puts you in a materially better position.
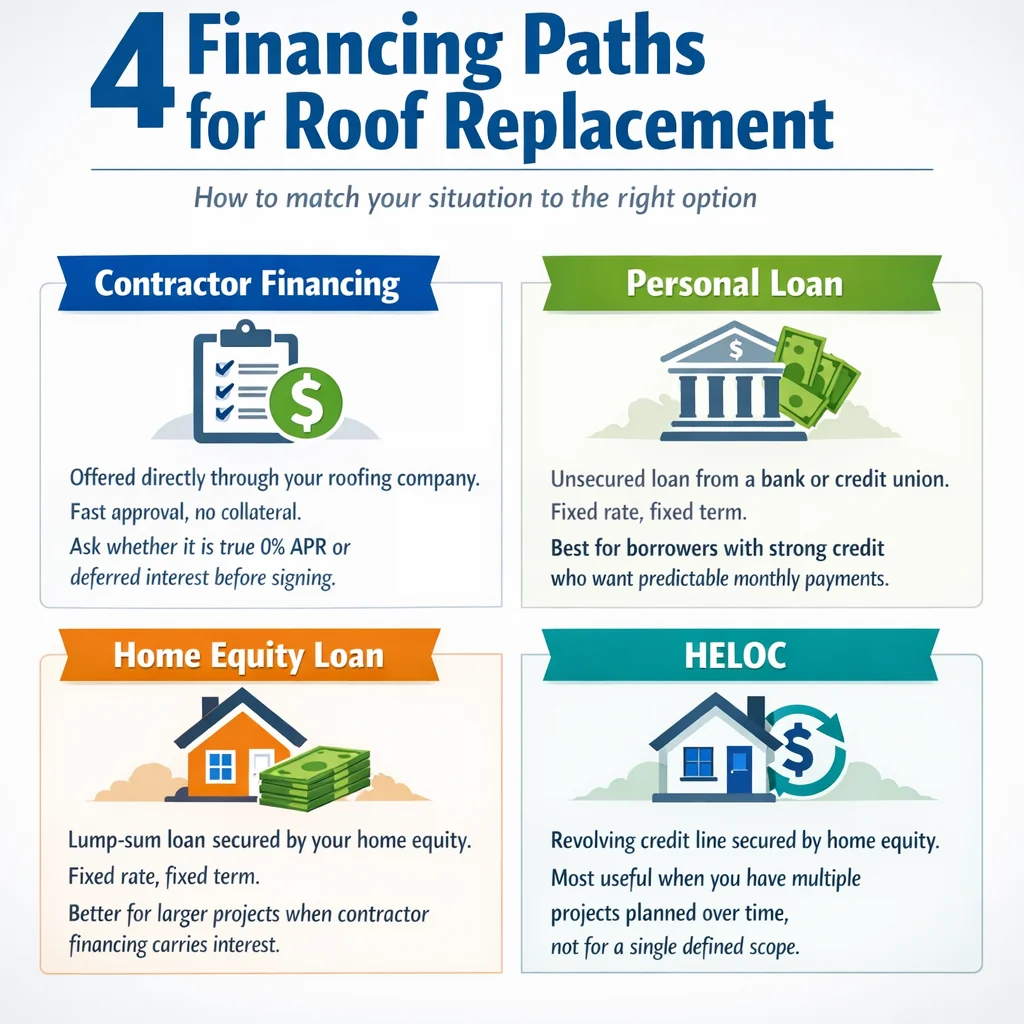
Many roofing companies, including Smithrock Roofing, offer financing arranged directly through the contractor, often in partnership with lending platforms. This approach is convenient because the application happens in the same conversation as your estimate, approvals can be fast, and no collateral is required. Whether you are looking at a full tear-off or a targeted replacement, our roofing service includes transparent financing options you can explore alongside your estimate.
The critical variable in contractor financing is the structure of the promotional offer. Two programs can both advertise zero percent interest and still be completely different instruments:
These are not the same protection. Before signing any contractor financing agreement, ask one direct question: “Is this a true 0% APR loan or a deferred interest promotional offer?” The answer changes your repayment obligation significantly. A note about prepayment penalties is not a substitute for that answer. No prepayment penalty simply means you will not be charged for paying early. It says nothing about what happens if you do not pay the full balance before the promotional period ends.
Unsecured personal loans from banks and credit unions are a straightforward alternative for homeowners who qualify. These carry fixed interest rates and fixed repayment terms, which makes monthly budgeting predictable. Because no home equity is pledged as collateral, your property is not at risk if your financial situation changes. Local institutions such as Truliant Federal Credit Union and SECU serve the Triad region and are worth contacting directly to compare terms alongside any contractor financing offer you receive.
A home equity loan provides a lump sum secured against the equity in your home, with a fixed rate and fixed repayment schedule. When contractor financing carries meaningful interest and you have substantial equity, a home equity loan can represent a lower-cost path. The tradeoff is that your home becomes collateral, which adds a layer of risk that contractor financing or personal loans do not carry.
A HELOC functions as a revolving credit line tied to your home equity. It offers flexibility because you draw only what you need, when you need it. That flexibility makes HELOCs most appropriate in specific circumstances: when you have several home improvement projects planned across an extended window, when a single lump-sum product does not match your project structure, or when contractor financing is not available at competitive terms.
What HELOCs are not well suited for is a single, defined-scope project like a roof replacement when true interest-free contractor financing is available. Using home equity for a project that could have been financed without pledging collateral depletes an emergency resource you may need for a more urgent purpose. HELOCs also frequently carry variable rates, which means your payment can shift over the life of the draw period.
Need a hand with this in Winston-Salem, Greensboro and the Triad? Call (336) 971-0464 or request a free estimate. Honest answers, no pressure.
One of the most consistent gaps in how contractors discuss financing is treating credit as a simple pass or fail. In reality, your credit profile does not just determine whether you qualify. It determines which financing path you should explore first.
| Credit Tier | Recommended First Path | Key Considerations |
|---|---|---|
| Excellent (760+) | True 0% APR contractor financing or personal loan | Widest option set; prioritize products with no deferred interest risk |
| Good (700-759) | Contractor financing or personal loan | Confirm APR structure; compare personal loan rates at local credit unions |
| Fair (640-699) | Contractor financing | Approval likely but terms vary; ask specifically about deferred interest |
| Below 640 | Contractor financing or secured options | Fewer unsecured options; verify terms carefully before committing |
Knowing your approximate credit tier before any conversation with a contractor or lender means you walk in with realistic expectations and are not surprised by terms at the point of signing. Many pre-qualification tools allow you to check eligibility without triggering a hard credit inquiry, so there is no cost to gathering that information early.
Every competitor in this space presents the financing application as a matter of convenience: apply before or after your estimate, whichever suits you. That framing undersells a genuinely important strategic point.
Pre-qualifying for financing before you collect estimates gives you a defined budget ceiling. With that ceiling established, you can evaluate whether any contractor’s quote fits within your approved financing range, rather than receiving a single quote and working backward to find financing that covers it. Pre-qualification at this stage typically involves a soft inquiry with no credit score impact.
The sequence that puts you in the strongest position:
Final application should follow contractor selection, not precede it. Completing a hard inquiry before you have selected a contractor provides no advantage and advances the credit pull without purpose.
Roof damage is rarely static. When underlayment is compromised or flashing has failed, water intrusion can extend damage to sheathing, insulation, and interior framing over time. A project that could have been addressed at a contained scope may grow in complexity the longer it is deferred. If you are unsure whether your roof has reached replacement territory, our article on when to replace a roof in Winston-Salem walks through the key indicators to watch for. Understanding your financing options before urgency forces the decision gives you more control over the process, more time to compare offers carefully, and a better chance of choosing the right product for your situation rather than the fastest available one.
When you are spreading the cost of a roof replacement over time, the longevity of the work you are financing becomes directly relevant to its value. A roof that needs attention again in a few years while financing payments are still active is a poor outcome regardless of how favorable the original loan terms were.
At Smithrock Roofing, we install CertainTeed Landmark shingles and hold CertainTeed PREMIER ShingleMark Master Certification, a distinction that reflects both the materials we use and the installation standards we are held to. Our work carries a 5-year labor warranty alongside the manufacturer’s limited lifetime warranty. With more than 350 five-star Google reviews and an A+ BBB rating, our track record with roofing in Winston-Salem and across the NC Triad is something you can verify before you commit to anything.
Financing a roof replacement is a sound decision when the terms are right and the work will last. Our job is to make sure both conditions are met.
Homeowners in Winston-Salem and the broader NC Triad generally have access to several financing paths, including personal installment loans through banks or credit unions, home equity loans or lines of credit, manufacturer-backed financing programs, and payment plans offered directly through roofing contractors. The right option depends on your credit profile, how much equity you have in your home, and how quickly you need the work completed.
It depends on the type of inquiry the lender initiates. A pre-qualification check typically uses a soft pull, which does not affect your credit score. A formal loan application triggers a hard inquiry, which can cause a temporary dip. If you are comparing offers from multiple lenders, try to submit applications within a short window so that credit bureaus are more likely to treat them as a single inquiry rather than multiple separate events.
When the loan terms are reasonable and the installation quality is high, financing can be a responsible way to address a necessary repair or replacement without depleting savings or delaying critical work. The key is ensuring that the roof you are financing will hold up well over the life of the loan. A durable installation backed by strong material and labor warranties reduces the risk that you will face additional costs while still making payments on the original project.
Verify that the contractor is licensed, insured, and holds recognized manufacturer certifications. Check their reviews on Google and their rating with the Better Business Bureau. Ask specifically about the materials they use, what warranties apply to both labor and product, and how long they have been serving your area. A contractor with a verifiable local track record gives you far more confidence that the work will be done correctly and that they will be available if any issues arise after installation. Our article on evaluating a roofing contractor in Winston-Salem covers the full vetting process in detail.
Homeowners in Winston-Salem and Kernersville deserve a roofing contractor they can trust with both the quality of the work and the transparency of the process, and that is exactly what Smithrock Roofing is built to deliver. With CertainTeed PREMIER ShingleMaster certification, a 5-year labor warranty, and more than 350 five-star Google reviews across the NC Triad, we bring proven craftsmanship to every project we take on. If you are ready to talk through your roof replacement and explore financing options that make sense for your situation, call us at (336) 971-0464 or Contact Smithrock Roofing to get started with a free estimate.
Smithrock Roofing © Copyright 2026 • All Rights Reserved • Privacy Policy • Maintained by Mongoose Digital Marketing